Looking to Sell a Home
in East County California?
Here's What You Need to Know About Selling a Home in East County...
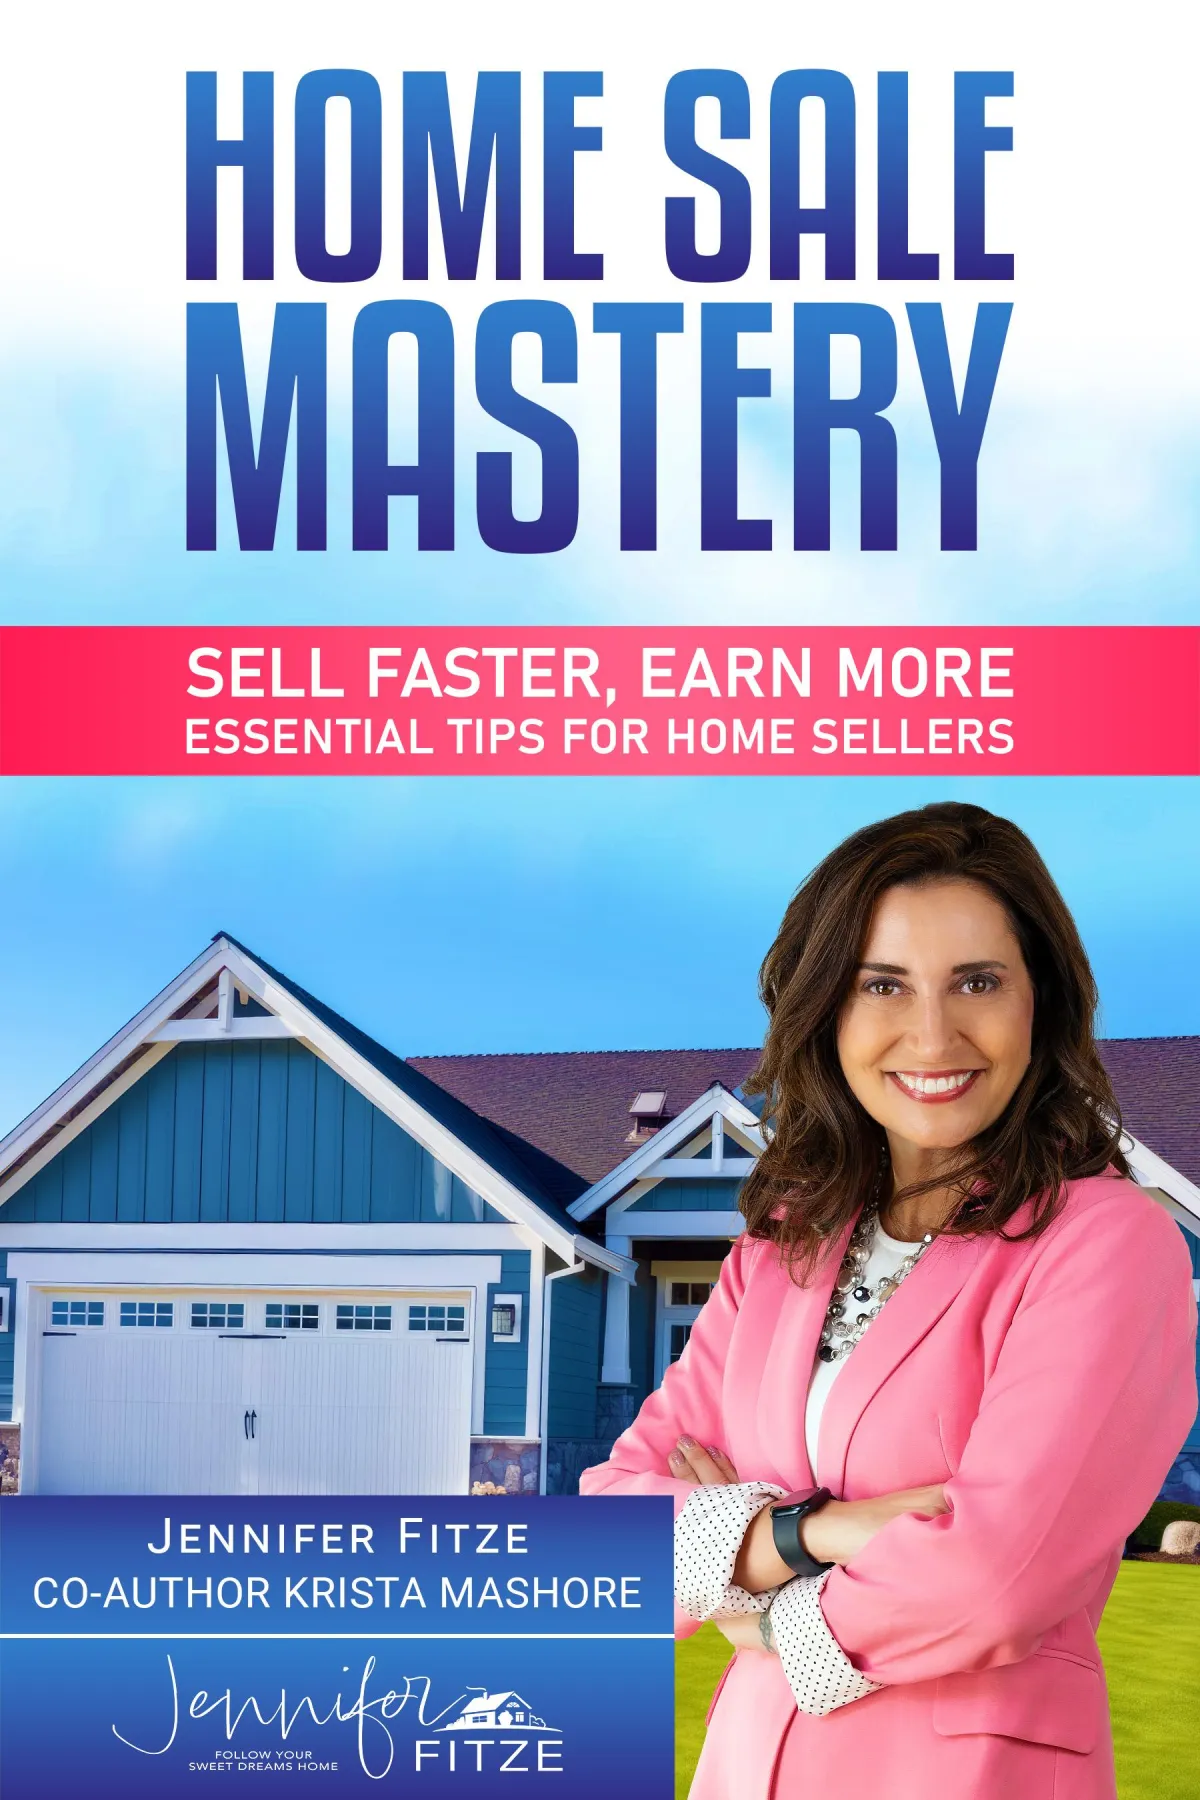
HOME SALE MASTERY
SELL FASTER. EARN MORE.
Essential Tips for Home Sellers in
Central Maryland & Southern Pennsylvania
Virtual Home Seller's Course
Guide to Mastering the Home Sale Process-Intro
Module 1: Choosing Your Agent
Module 2: Marketing in Today's World
Module 3: Supercharging Traditional Marketing
Module 4: Compensation/Commissions
Module 5: Mastering Negotiations
Module 6: The Importance of Communication
Module 7: Master Sellers Goals and Priorities
Module 8: Getting Clarity
Module 9: How to Prepare for a Great Sale
Module 10: Do's and Don'ts When Selling Your Home
Exclusive Market Updates
I know selling a property can be stressful and overwhelming! That’s why I've got you covered. With the right Realtor by your side, I will guide and navigate you through the selling process to help you make informative decisions and get the best terms possible on your sale!
My exclusive market updates will help you stay ahead of the curve-from the latest listings, price trends and days on market, I ensure you will have all the information you need to make informed decisions on your sale. Central Maryland and Southern Pennsylvania's real estate landscape is dynamic, and with my expert analysis, you will always be well informed and in the know.
Considering Selling?
Selling a home can be an exciting but also challenging experience. If you're planning to sell your Maryland or Southern Pennsylvania home, it's important to be prepared and aware of what to expect throughout the process. This short guide is designed to provide Sellers like you with valuable insights and tips to navigate the sale of your home successfully.
DOWNLOAD TO ACCESS:
The Complete Guide to Selling A Home
Spring is here!
The Spring Real Estate Market is thriving, and we are seeing a significant increase in demand for homes in Voorhees, especially from millennials.
In fact, the current absorption rate in our area is only 3 months, which means that if no more homes come on the market, we will only be able to sustain the current demand for up to 3 months.
This is great news for anyone considering selling their home, as the high demand can lead to a boost in your bottom line.
If you are thinking about selling your home, now is the perfect time to do so. To get started, it's essential to focus on your curb appeal, which can significantly impact the value of your property. That's why we've put together a helpful checklist to help you get started.
Friendly reminder: Before you make a repair, be sure to check with a real estate agent to make sure it is worth your return on investment. Feel free to Book A Call with me if you have any questions or want a free consultation!
Are you a little behind on your spring cleaning? Grab a copy of the Ultimate Spring Cleaning Checklist that was featured last month.
Preparing for a possible move this summer? Click to the right to check out our moving checklist to get your whole house ready for the next home!
DOWNLOAD TO ACCESS:
30 Day Plan to Prepare Your Home for Sale
DOWNLOAD TO ACCESS:
The Complete Guide to Selling A Home
market Updates
buying new construction? buyer beware
Local market update
NAR's Commission Settlement:
Understanding Buyer's Agent Compensation
National Market Update
Buyer Tips
Community Videos
3 best sandwich Shops
Best Burrito in Brentwood
Best Hot Dogs in Brentwood
MJ's Cafe in brentwood
Welcome To The Virtual Seller seminar For
Central MAryland
If you are a homeowner either thinking about selling or already made the decision to sell, but still have questions or concerns regarding the process, price or anything else, you are in the right place.
This free seller seminar will give you the exact step by step blueprint on everything you need and guide you through the selling process, so you can make the best decision on selling your home for top dollar.
You will learn about marketing your home, timelines, pricing, negotiations and so much more.
Take a look around and let me show how I can help you.
Jennifer Fitze, Realtor, Broker Associate
Berkshire Hathaway HomeServices PenFed Realty
Licensed in Maryland & Pennsylvania
Welcome To The Virtual Seller Seminar Library
Learn the latest and most up to date marketing and sales tactics
to sell your home for top dollar.
The Pre-Market Quiz
"Will your home pass the test before going to market?"
Learn how to sell your home for top dollar right now
You may need to make a few changes before selling
Pre-Market Timelines
"Let's talk about the timelines before listing a home with me."
What you should expect when getting your home ready to sell
How to maximize the return on your investment
Timing
"How quickly will my home sell? This is a common question I get."
Learn about the market climate and absorption rates
The market climate will determine how quickly your home will sell
Marketing Your Home
"The importance of marketing your home properly."
Digital marketing exposes your property to the masses
Negotiation will be key in selling your home
Pricing your home is not as easy as checking Zillow
Home Valuation
"How do you determine what your house is worth?"
Pricing your home right
Factors to consider are size, condition, location, marketing, and negotiating
Underpricing and overpricing your home will cause you to lose money
Is Zillow Accurate?
"Should I use Zillow as an accurate evaluation of my home’s value?"
Zillow is an algorithm based on public data
Zillow has never seen the inside of your home and it’s a computer
Zillow comes up with the value based upon what your neighbors are selling for
What to Disclose?
To disclose or not to disclose
This is vital to ensure that you are safe during and after the sale
Over-disclosure is better than under-disclosure
Receiving Offers
"How do you know if you should accept the offer you just got?"
What if you don't receive the amount of offers you were hoping for?
What happens if we have more than one offer?
Good Time to Sell?
"Are we heading into a recession and is now a good time to buy and sell?"
If you're fearful of selling due to a recession, you may want to think again
Remember, it's all relative
Negotiations
"How to negotiate like a master to make sure you get the most out of your home?"
How to get top dollar when selling
Walking away with the most amount of money in your pocket
Inspections?!
"Should you get inspections done prior to listing?"
The advantages of having inspections done prior to listing
Saves you time and money
Curb Appeal
How to make a good first impression
How to get maximum exposure and top dollar
There are simple tricks that can save you money and maximize the return on your investment at the same time
Should I Take the First Offer?
NO NO NO!
The goal is for your home to be seen by the masses
Then, to get the highest and best price and terms for your home
What Are Contingencies?
"When a buyer has made an offer on a home and the seller has accepted it but the final sale is contingent on certain criteria being met."
This criteria, or contingencies, typically fall under four major categories: appraisal, loan approval, inspections and reports & disclosures
Contingency Timeframes
"Now we're under contract prior to contingencies being removed."
The buyer now will secure their loan, have their inspections on the property, and review all of the reports and disclosures
WANT TO GET A FREE CUSTOM MARKET PROPOSAL?
Go to the next page to request a custom market proposal for your specific home
Lets Get You Prepared To Sell A Home
MEET THE TEAM
Here's your team that will help you throughout the
entire selling & buying process
Krista Mashore Realtor & Broker
DRE # 01346304
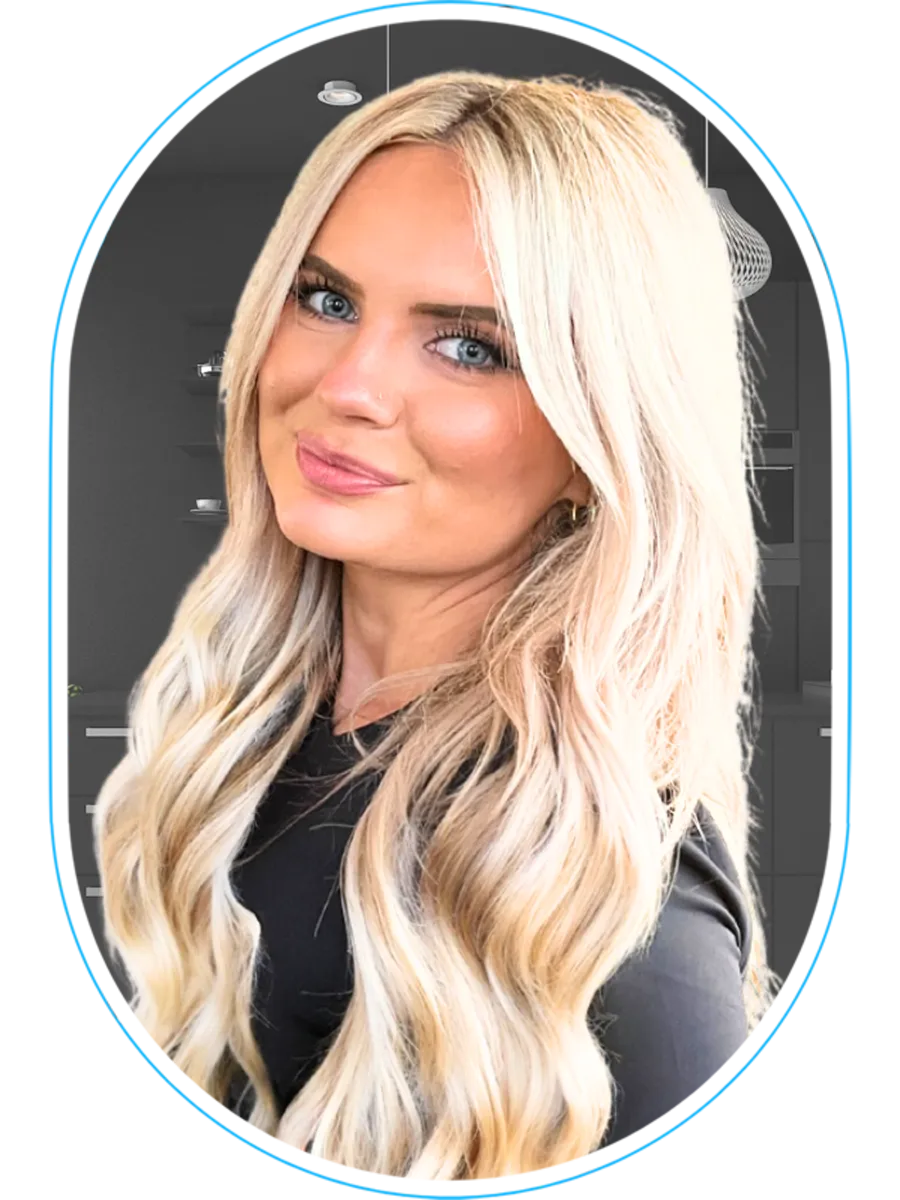
Jaynlin Miller Marketing and Seller Specialist
DRE #02195224
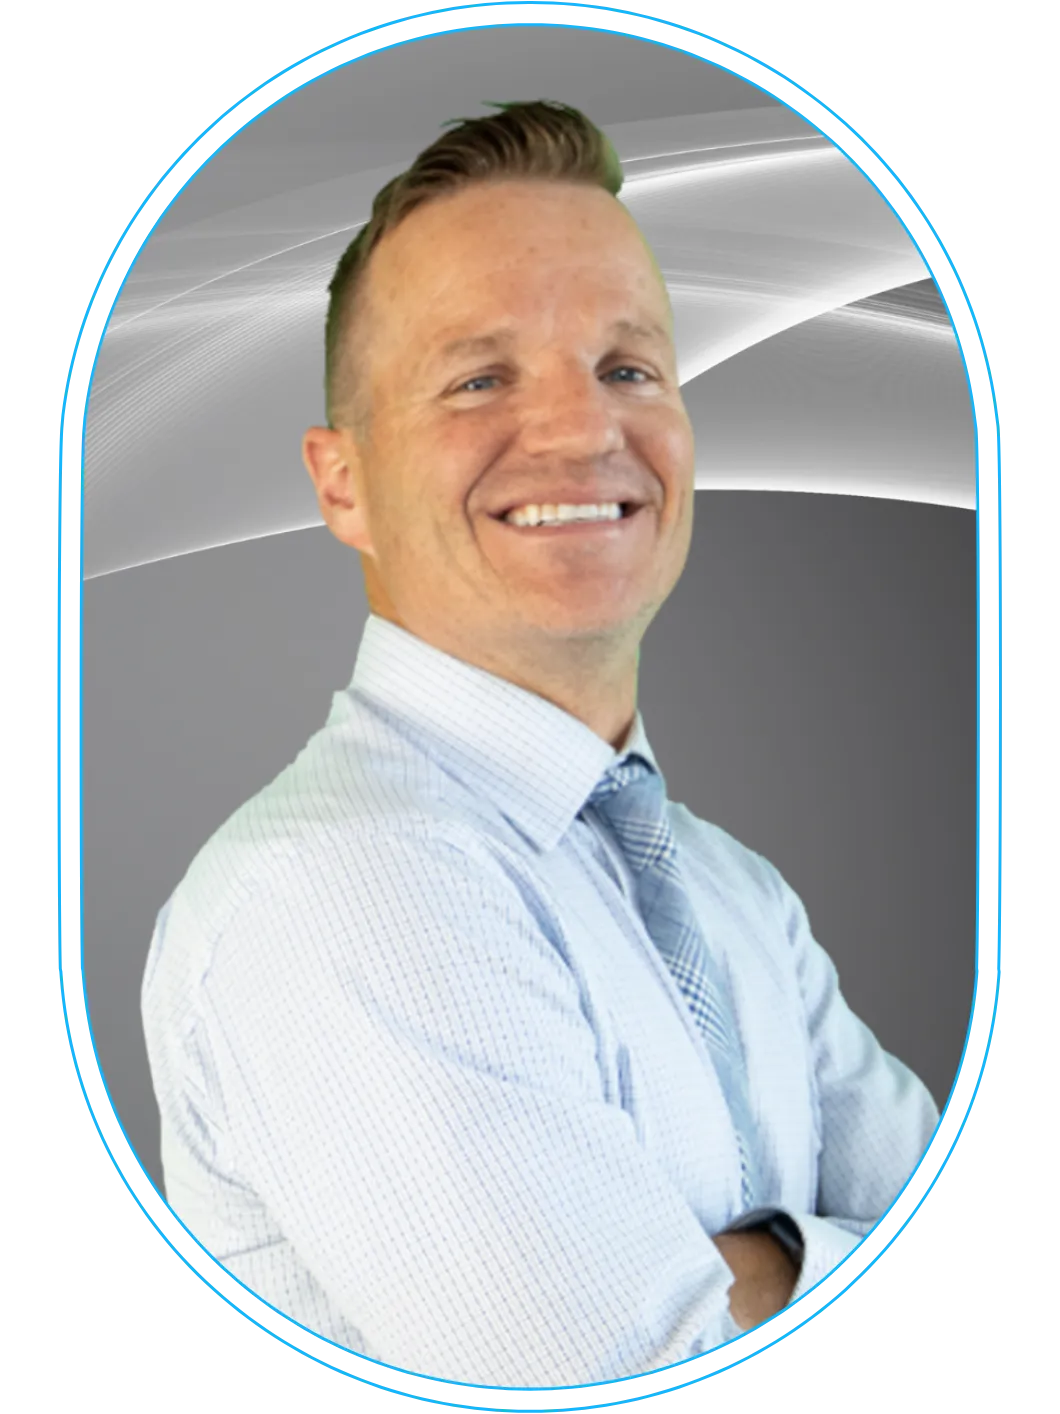
Josh Vitale
Listing Specialist
DRE #02009638
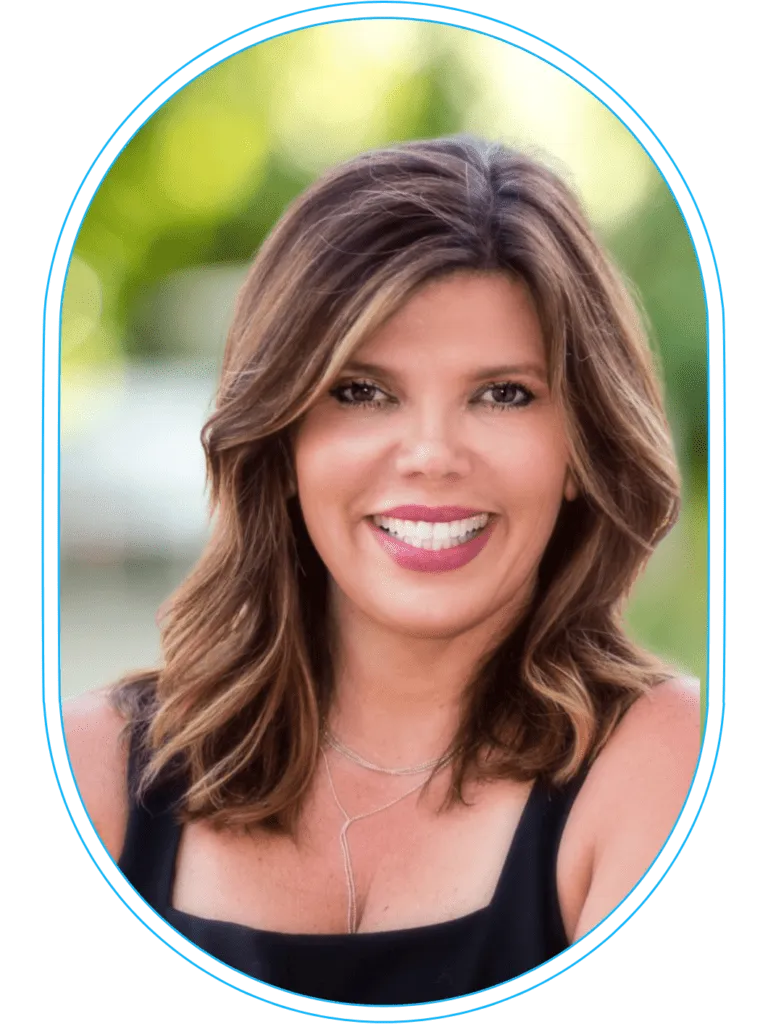
Heidi Kugl
Buyer’s Specialist
DRE #01329047
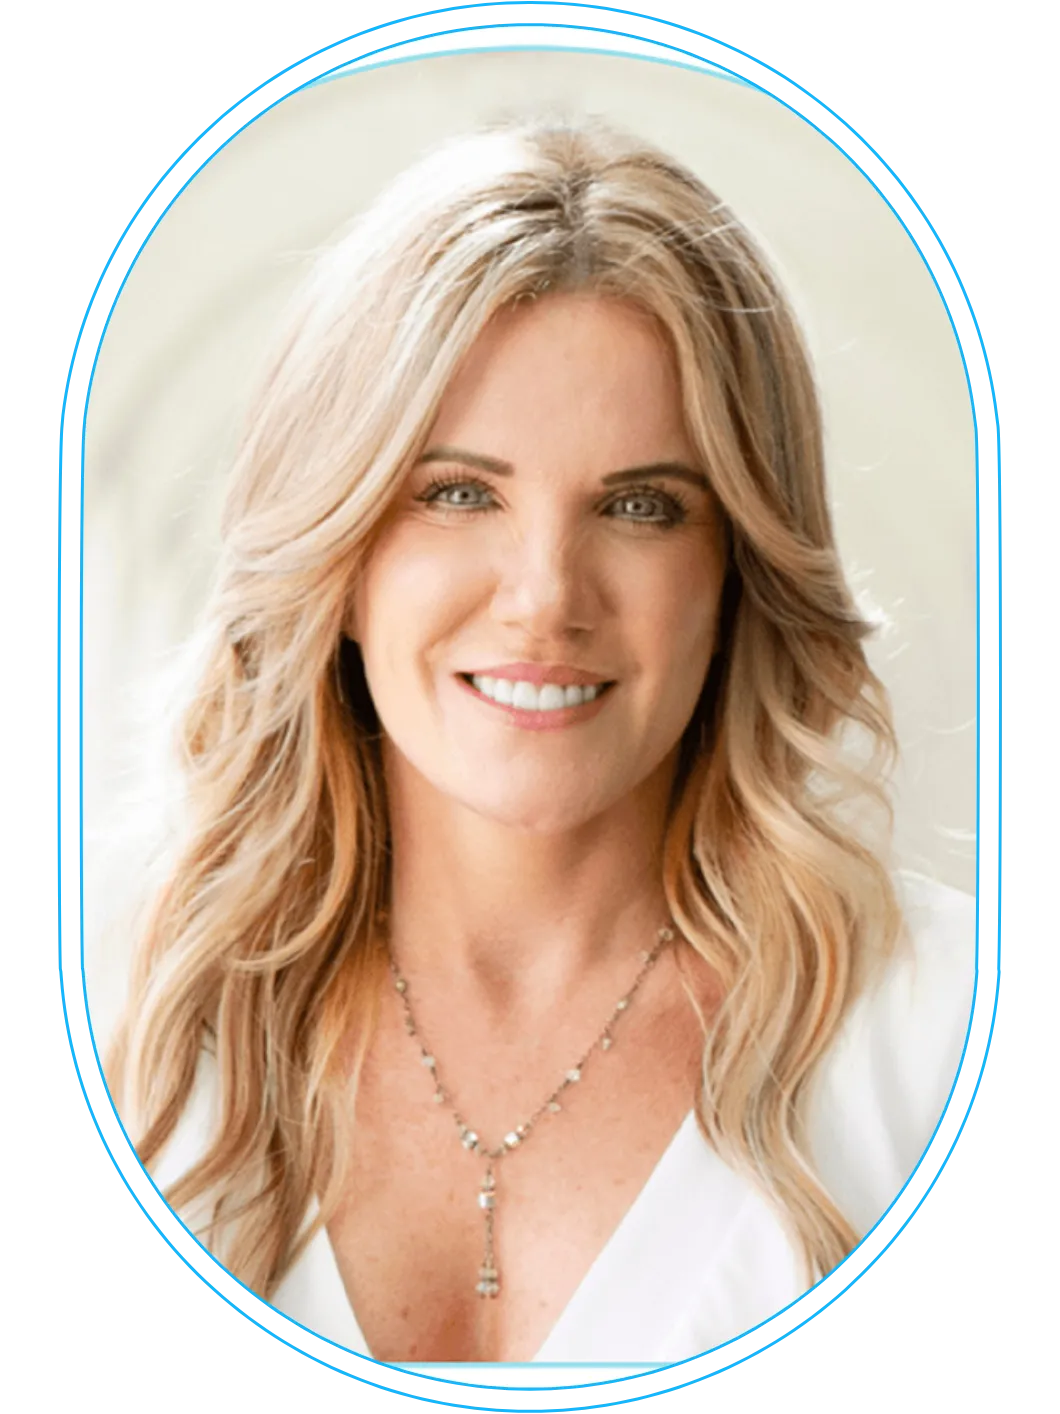
Krista Mashore | Realtor & Broker
DRE # 01346304
Jaynlin Miller | Marketing and Seller Specialist
DRE #02195224
Josh Vitale | Listing Specialist
DRE #02009638
Heidi Kugl
Buyer’s Specialist
DRE #01329047
Jennifer Fitze | Realtor & Broker
Licensed in MD & PA
Meet Jennifer Fitze
Jennifer Fitze, is a name synonymous with expertise and success in the real estate world. Licensed as a Realtor since 2005, Jennifer has dedicated her career to serving the communities of Maryland, Pennsylvania, and Delaware. Her exceptional skills and unwavering commitment have ranked her in the top 4% of agents in Maryland, a testament to her proficiency in the field. As a proud member of both the Maryland Association of Realtors and the Harford County Board of Realtors, Jennifer upholds the highest standards of professionalism. Her illustrious career is further highlighted by her membership in the Million Dollar Real Estate Association, showcasing her ability to handle high-value transactions with ease. Holding an Associate Broker's license, Jennifer's expertise is not just theoretical but backed by impressive experience. Having sold over 500 homes, she brings a wealth of knowledge and insight, invaluable to anyone looking to navigate the complexities of the real estate market.
Residing in the town of Bel Air, MD, with her Husband, Son, and adorable boxer pups, Jennifer's life is a beautiful blend of professional excellence and personal joy. Her passion for baking and her remarkable achievement of running the New York Marathon reflect her dedication and zest for life, qualities she brings into every aspect of her work.
For more insights and tips from Jennifer on how to sell your home for top dollar, visit her on Instagram, Tik Tok, YouTube, and Facebook.
Visit my social media pages for more real estate tips, home tips, and local information!
How Much Money Will I Actually Walk Away With After Selling My Home in Bel Air, Maryland?
How Much Money Will I Actually Walk Away With After Selling My Home in Bel Air, Maryland?
The money you walk away with is called your net proceeds.
It's your sale price, minus everything that gets paid out of the sale at settlement.
For most Bel Air sellers, that list includes:
Your mortgage payoff, plus any home equity loan or line of credit
Real estate commission, as agreed in your listing agreement and your contract
Your share of Maryland and Harford County transfer and recordation taxes, as set by your contract
Settlement and title charges on the seller's side
Property tax and other prorations, depending on what's been paid and when you settle
Any credits or repairs you agreed to give the buyer
Anything else tied to the property, like HOA or condo fees, liens, or a final water bill
The simplest way to know your number is to ask for a seller net sheet before you list, and again every time an offer comes in.
A net sheet is a line-by-line estimate of what you'll take home at a specific price and set of terms.
Jennifer Fitze is a Realtor, Associate Broker with COMPASS in Bel Air, Maryland, helping buyers and sellers throughout Bel Air and Harford County make informed real estate decisions.
What Are Net Proceeds, Exactly?
Net proceeds are the dollars that actually reach you after settlement.
Not the list price.
Not the offer price.
Not even the final sale price.
It's what's left after the settlement company pays off your loans, pays the costs you owe, and settles up credits and prorations with the buyer.
Here's the basic formula:
Sale price - mortgage and lien payoffs - selling costs - prorations owed - credits to the buyer + prorations owed to you = net proceeds
Every one of those pieces can change based on your contract.
That's why the number is an estimate until your final settlement statement is ready.
Why Is My Net Different From My Sale Price?
Because a home sale pays a lot of people before it pays you.
Your lender gets paid back first.
Then the costs of the sale are paid, including commission and government taxes and fees.
Then you and the buyer settle up on bills that cover part of the year, like property taxes.
Many sellers are surprised by how many line items show up on the settlement statement.
None of them should be a surprise if you've seen a net sheet ahead of time.
What Comes Out of My Sale Price?
Let's go through the main categories one at a time.
Your mortgage payoff
Your loan balance on your monthly statement is not your payoff amount.
Your payoff includes:
The remaining principal
Interest that has built up since your last payment
Any fees your lender charges to close out the loan
The settlement company requests an official payoff statement from your lender, good through a specific date.
If you have a second mortgage, a home equity loan, or a home equity line of credit, those are paid off at settlement too.
A home equity line of credit usually needs to be closed, not just paid down. Your settlement company will help with that.
Real estate commission
Commission is negotiable.
What you pay your listing agent is set in your listing agreement.
If you agree to offer or pay anything toward the buyer's agent's compensation, that's spelled out in writing too, and it can come up during negotiations on a specific offer.
Your net sheet should show commission based on what you've actually agreed to, not a guess.
Transfer and recordation taxes
When a home changes hands in Maryland, the state and the county collect taxes when the deed is recorded.
In Harford County, that typically means a state transfer tax, a county transfer tax, and a recordation tax.
Who pays which part is set by your contract.
Your agent and your settlement company can tell you what's customary in Harford County and what your contract says.
Some details can change the math, including whether the buyer qualifies for a first-time buyer exemption.
Ask for these taxes to be shown line by line on your net sheet.
Settlement and title charges
There are usually some fees on the seller's side of the settlement statement.
These can include:
A settlement or closing fee
Deed preparation
Release fees for recording the payoff of your mortgage
Courier or wire fees
The amounts depend on the settlement company and your situation.
Your settlement company can give you their fee schedule.
Prorations
Some bills cover a period of time, and settlement divides them fairly between you and the buyer.
The big one is usually property taxes.
In Maryland, property taxes are typically billed for a fiscal year that runs July 1 through June 30.
If you've already paid the bill for the year, the buyer may owe you a credit for the days after settlement.
If the bill hasn't been paid, you may owe the buyer a credit for the days you owned the home.
Other items that may be prorated or settled include:
HOA or condo fees
Water and sewer charges, if your home is on public utilities
Ground rent, if your property has it
Prorations can work in your favor or against you, depending on timing.
Credits and repairs
If you agree to a credit toward the buyer's closing costs, or a credit after the home inspection, that comes off your proceeds.
If you agree to make repairs instead, that money comes out of your pocket before settlement, or is paid at settlement if the contractor is paid that way.
Both affect your bottom line.
Liens, judgments, and other payoffs
Anything recorded against your property must usually be cleared at settlement.
That can include:
Unpaid contractor or mechanic's liens
Judgments
Unpaid municipal charges
Your settlement company's title search should find these.
It's much better to know about them before you list than to find out the week before settlement.
What Is a Seller Net Sheet?
A seller net sheet is an estimate of your take-home money at a specific price.
A good one shows:
The sale price
Your estimated mortgage payoff
Commission, based on what you've agreed to
Your share of transfer and recordation taxes
Estimated settlement and title charges
Estimated prorations
Any credits to the buyer
Your estimated net
You should see one at three points:
Before you list, at your planned list price
With every offer, using that offer's price and terms
After the inspection and appraisal, if anything changed
The net sheet is an estimate, not a guarantee.
Your final numbers come from the settlement statement your settlement company prepares before closing.
How Do I Compare Offers by Net, Not Just Price?
The highest price isn't always the most money in your pocket.
Two offers at similar prices can net very differently.
Here's what to look at alongside price:
Seller credits. A credit toward the buyer's closing costs comes straight off your proceeds.
Who pays which taxes and fees. These terms are in the contract.
Settlement date. It affects your mortgage interest, prorations, and how long you carry the home.
Contingencies. An offer with an inspection or appraisal contingency can lead to renegotiation later.
Financing type. Some loan programs come with appraisal or repair requirements.
Ask your agent to run a net sheet on each offer side by side.
That turns "which offer is bigger?" into "which offer is better for me?"
How Does Timing Affect What I Walk Away With?
Timing matters more than most sellers expect.
Every extra month you own the home, you're paying:
Mortgage interest
Property taxes
Insurance
Utilities
HOA fees, if you have them
Your settlement date also affects prorations and the exact payoff amount.
For context, in Bel Air ZIP codes 21014 and 21015 in September 2026, Bright MLS showed an average list price of $498,530 and an average sold price of $482,716.
Those are averages across different homes, so they don't tell you what any one home will sell for.
But they're a reminder that the price you list at and the price you settle at are often not the same.
Pricing well from the start, and preparing the home for showings, helps protect both your price and your timeline.
Do I Owe Taxes on the Profit From Selling My Home?
It depends on your situation.
Federal tax law lets many homeowners exclude some or all of the gain on the sale of their main home if they meet ownership and use tests.
IRS Publication 523, "Selling Your Home," explains the rules.
Things that can change the answer include:
Whether the home was your main residence
How long you owned it and lived in it
Whether you rented it out or used part of it for business
What you paid and what improvements you made
If you're not a Maryland resident when you sell, Maryland may require tax to be withheld from your proceeds at settlement.
Different federal rules can apply if the seller is not a U.S. person.
Talk with your CPA or tax advisor before you list.
Your agent and settlement company can't give tax advice, but they can make sure your advisor has the numbers they need.
What If I Owe More Than My Home Is Worth?
If your payoff is higher than what the home is likely to sell for after costs, you may need to bring money to settlement.
In some cases, sellers work with their lender on a short sale, where the lender agrees to accept less than the full payoff.
Short sales take more time and require lender approval.
If you think you might be in this situation, talk with your lender, a real estate attorney, and your agent early.
The sooner you know, the more options you have.
When Do I Actually Get My Money?
At settlement, after the documents are signed and the funds are ready to be released.
Your settlement company will tell you how you'll receive your proceeds, usually by wire transfer or check.
A few safety tips:
Confirm wire instructions by phone with your settlement company, using a phone number you already know is real.
Never trust wiring instructions that arrive by email alone, especially if they change at the last minute.
Bring proper ID to settlement.
Wire fraud targets home sales because large amounts of money are moving.
A quick phone call protects your proceeds.
Scenario #1: The Seller Who Used the Monthly Statement
A Bel Air seller estimated their profit using the loan balance on their monthly mortgage statement.
When the settlement company ordered the official payoff, it was higher because of interest built up since the last payment.
Their agent had flagged this on the net sheet, so it wasn't a shock.
The lesson: always estimate with your payoff amount, not your statement balance.
Scenario #2: Two Offers, Different Nets
A Harford County seller received two offers.
One had a higher price but asked for a seller credit toward the buyer's closing costs.
The other had a slightly lower price, no credit, and a settlement date that matched the seller's move.
Their agent ran a net sheet on each one.
The lesson: compare offers by what you take home, not by the headline price.
Scenario #3: The Forgotten Home Equity Line
A seller had opened a home equity line of credit years ago for a kitchen project and forgot it was still open.
The title search found it.
It was paid off and closed at settlement, which lowered the seller's proceeds from what they'd pictured.
The lesson: tell your agent and settlement company about every loan or line tied to the house before you list.
Scenario #4: The Post-Inspection Credit
After the home inspection, a buyer asked for repairs.
The seller and buyer agreed on a credit instead.
The credit came straight off the seller's proceeds at settlement.
The lesson: when you negotiate repairs or credits, ask for an updated net sheet before you agree.
Scenario #5: The Tax Question Nobody Asked
A seller had rented out their home for a few years before deciding to sell.
They assumed they'd owe no tax on the gain.
Their CPA explained that the rental years could change the answer.
The lesson: talk with a tax advisor before you list, especially if the home wasn't always your main residence.
Common Mistake: Using the List Price as Your Number
Your list price is a starting point.
Plan around a realistic sale price and a real net sheet.
Common Mistake: Using Your Statement Balance Instead of a Payoff
Interest and fees make the payoff higher than the balance you see each month.
Ask for an estimate using a realistic settlement date.
Common Mistake: Forgetting About Second Loans and Liens
Home equity loans, lines of credit, and recorded liens must usually be cleared at settlement.
Tell your agent about all of them up front.
Common Mistake: Comparing Offers by Price Alone
Credits, settlement dates, and contingencies all change your net.
Run a net sheet on every offer.
Common Mistake: Agreeing to Credits Without Re-Running the Numbers
Every credit or repair agreement changes your bottom line.
Ask for an updated net sheet before you sign an addendum.
Common Mistake: Skipping the Tax Conversation
Whether you owe tax on the sale depends on your situation.
Talk with your CPA before you list, not after you settle.
Jennifer's Local Perspective
I've been helping people buy and sell homes in Bel Air and Harford County for 21 years.
The first question most sellers ask me isn't "what's my house worth?"
It's "what will I walk away with?"
That's the right question, because it's the number that decides where you can move next.
So before we talk about a list price, I like to sit down and walk through a net sheet together.
We look at your payoff, your selling costs, your share of the transfer and recordation taxes, and the prorations, line by line.
Then, when offers come in, we run the numbers on each one so you can see the real difference between them.
For context, my listings have averaged 9 days on market since January 1, 2021, based on Bright MLS data I pulled on October 15, 2026.
Every home and every market is different, so that's history, not a promise.
What I can promise is that you'll see the numbers before you make a decision, with no pressure along the way.
Frequently Asked Questions
How do I figure out how much I'll make selling my house in Bel Air?
Start with a realistic sale price, then subtract your mortgage payoff, commission, your share of transfer and recordation taxes, settlement charges, any credits to the buyer, and prorations. A seller net sheet from your agent puts all of that on one page.
What is a seller net sheet?
A seller net sheet is an itemized estimate of what you'll take home at a specific price and set of terms. You should see one before you list and with every offer.
Who pays transfer taxes when I sell a home in Maryland?
It's set by your contract. Your agent and settlement company can tell you what's customary in Harford County and how your specific contract divides those taxes.
Is my mortgage payoff the same as my loan balance?
No. Your payoff includes interest that has built up since your last payment and any lender fees. The settlement company orders an official payoff statement good through a specific date.
Will I owe taxes on the profit from selling my home?
It depends on your situation. Many homeowners can exclude some or all of the gain on their main home if they meet certain tests. IRS Publication 523 explains the rules, and your CPA can tell you how they apply to you.
When will I get my money after selling my home?
At settlement, once documents are signed and funds are ready to be released. Always confirm wire instructions by phone with your settlement company before any money moves.
Can Jennifer Fitze help me estimate my net proceeds before I sell my home in Bel Air, Maryland?
Yes. Jennifer Fitze is a Realtor, Associate Broker with COMPASS in Bel Air, Maryland, with 21 years of experience helping sellers throughout Bel Air and Harford County understand their numbers, compare offers by net, and plan their next move with confidence.
Final Thoughts
How much money will you actually walk away with after selling your home in Bel Air, Maryland?
Your sale price, minus what the sale pays out first.
That means:
Your mortgage payoff and any other loans or liens
Commission, as you've agreed in writing
Your share of transfer and recordation taxes, as set by your contract
Settlement and title charges
Prorations for property taxes and other shared bills
Any credits or repairs you agree to
You don't have to guess at any of it.
A net sheet before you list, and with every offer, shows you the number that matters most.
Call to Action
Thinking about selling your home in Bel Air or anywhere in Harford County?
A conversation before you list can help you see your real numbers and plan your next move with confidence.
Jennifer Fitze is a Realtor, Associate Broker with COMPASS in Bel Air, Maryland, helping buyers and sellers throughout Bel Air and Harford County make informed real estate decisions.
Jennifer Fitze
Realtor, Associate Broker
COMPASS
528 S. Main St.
Bel Air, MD 21014
📞 443-504-7830
WHAT PEOPLE ARE SAYING ABOUT JENNIFER FITZE...
Jen is the most realistic and down to earth, knowledgeable real estate agent!
"We had the best experience with her during our multiple home sales and purchasing of homes! You need an expert in selling your home? Thats Jen. She is a published author in selling homes. You need an expert in purchasing a home? Thats Jen. She works day and night FOR YOU. Being a realtor means more to Jen than other agents. This is her passion. Buying or selling a home will be stressful; however, with Jen, you are guaranteed to be less stressed. Just meet with her and see for yourself. ❤️"
- Jennifer G. & Mike H.
Jen is a gem!
She always goes above and beyond to help her clients and is always willing to help them find their dream home!
"Jen is wonderful- so focused on what you are looking for. Makes selling or buying a home so easy to understand in the complicated world of real estate- I highly recommend, even if you are just needing information on how this all works and how to get started."
- Beth G.
Jen Fitze is a top notch Realtor!
"She makes the buying/selling process very easy. She knows what needs to be done to make your house presentable and sell quickly. She was available to show us homes, to find the perfect house when we were on a time contingence. She knows this business, which helps ease the stress. You’re not only gaining an agent with you go with Jen, but also a friend."
- Jim & Laura M.
Want to be sure you don't miss out on any local tips & local real estate market updates?
Have them delivered to your inbox.
Subscribe to the monthly digital newsletter below!
Jennifer Fitze | Copyright © 2024 | All Rights Reserved